
Strategy Dashboard
U.S. Midterms:
(Grid)Locked and Loaded
Q4 2026
As the November 3rd US midterm elections approach and Donald Trump’s Republican Party continues to poll poorly, investors are contemplating whether political gridlock would be good for markets. The logic is appealing. Divide control of Washington, make sweeping legislation harder to pass and give businesses greater certainty about the rules ahead. But before embracing that investment playbook, two qualifications deserve attention. Election results are not a foregone conclusion (looking at you, Brazil and British Columbia). And even if a divided government emerges, legislative paralysis would not necessarily bring policy stability.
For starters, congressional constraints apply unevenly. Major changes to taxes and spending generally require legislation, while the president retains considerable discretion over trade, sanctions and aspects of regulation. A Democratic majority in either chamber could constrain the administration through funding negotiations and oversight. However, investors expecting an automatic retreat from tariffs or a quieter foreign policy agenda could be disappointed. Policy uncertainty may simply migrate from Capitol Hill to executive agencies and courtrooms.
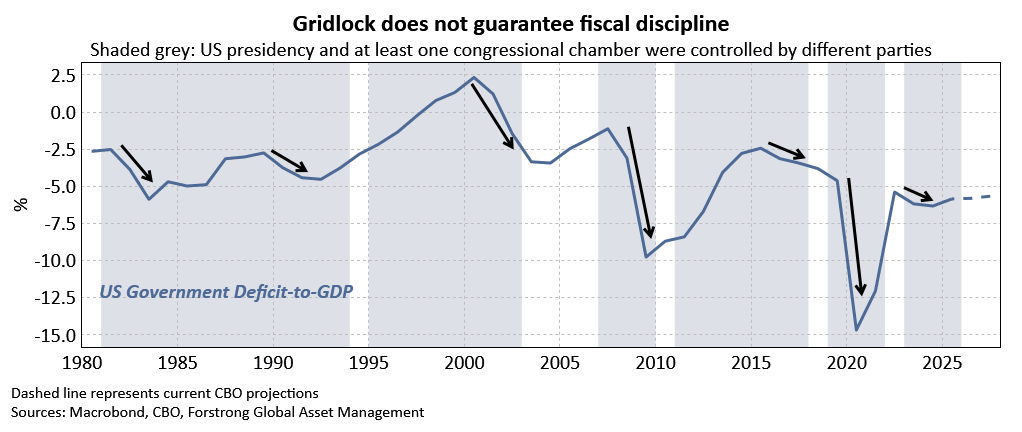
Fiscal policy presents another important distinction. Making new stimulus harder to enact does not immediately remove support already working through the economy. Existing tax provisions, previously approved spending and projects underway do not automatically disappear when congressional leadership changes. Gridlock could limit the next round of fiscal expansion without abruptly reversing the current one.
Conversely, persistent large deficits should not be mistaken for an ever-increasing growth tailwind. The economy responds partly to changes in fiscal support, not simply its absolute size. Spending can remain substantial while providing less additional impetus than before. This makes the timing and implementation of policy far more consequential than a snapshot of government deficit-to-GDP.
The implications for bonds are similarly nuanced. Constraints on additional stimulus could temper inflation expectations and future borrowing requirements; potentially easing pressure on yields. But a divided government offers no assurance of fiscal discipline. Large structural deficits could persist, while contentious funding and debt-limit negotiations introduce periodic volatility. Gridlock might restrain new commitments without resolving concerns about existing obligations.
Should Republicans retain both chambers, the legislative path to further tax and spending measures would be clearer. That could support corporate earnings and domestic investment. Yet the same policies could also sustain inflationary pressure and increase Treasury issuance, complicating the outlook for interest rates. There are thus important trade-offs for financial markets, irrespective of the election outcome.
The midterms matter, but translating the result into portfolio decisions requires more than identifying the winning party. We remain focused on corporate earnings, investment spending and the rising financing costs affecting governments, businesses and consumers alike. The election could alter their trajectory at the margin, but it is just one of many factors to consider.
For global investors, the opportunity set extends well beyond Washington. European defence and infrastructure initiatives, Asian manufacturing investment and corporate capital expenditures have their own drivers and timelines. A more constrained US fiscal agenda could increase the relative importance of these growth sources. But global diversification need not depend on a particular American political outcome.
Cash & Currencies
The yield on our preferred cash and equivalents exposure (a high interest savings account (HISA) ETF) has recently begun to trail behind money market ETF exposures, despite having a similar risk profile. We have modified our cash and equivalents composition this quarter; liquidating HISA exposure and initiating a money market exposure.
Bonds
In an environment of robust growth and sticky inflation, we expect the “path of least resistance” for long-term bond yields to be higher, even after a period of acute upwards pressure. Short-term bond yields are also grinding higher alongside central bank rate hikes, making the added interest rate risk at the long end of the curve even less attractive. We have maintained our underweight and short duration fixed income positioning this quarter.
Equities
The Chinese government’s priorities have become more skewed toward technological self-sufficiency rather than domestic demand reflation, raising the bar for the large, decisive stimulus that would typically help re-rate the onshore equity market. We have liquidated our exposure to onshore Chinese “A share” equities and invested the proceeds into a “core” broad emerging markets equity position in balanced and growth-oriented strategies this quarter.
Opportunities
Elevated gold prices are translating into wider margins and stronger free cash flow for major gold mining companies, supporting dividends, buybacks and balance sheet improvement. Constrained mine supply and improved capital discipline also support the gold majors, which provide a higher beta exposure to our structural gold investment thesis. We have initiated a position in gold mining equities in growth-oriented strategies this quarter.

Looking for perspective beyond the headlines?
The information contained in these materials is for general informational purposes only and is intended to provide only brief comments on broad market, industry or sector trends, or other general economic or market conditions. It is not intended to provide an overview of the terms applicable to any products or funds managed or sponsored by Forstrong Global Asset Management Inc. (“Forstrong”). Views expressed regarding a particular company, security, industry, investment, or market sector are the views only of that individual as of the time expressed and do not necessarily represent the views of Forstrong or any other person in the Forstrong organization. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. These views are not and may not be relied upon as investment advice and, because investment decisions for a Forstrong fund or product are based on numerous factors, are not and should not be relied upon as an indication of trading intent on behalf of any Forstrong fund or product. Any opinion or assumption may contain elements of subjective judgment and are not intended to imply, nor should be interpreted as conveying, any form of guarantee or assurance by Forstrong of any future action or performance. Neither Forstrong nor any of its affiliates, businesses, or representatives make any representation or warranty, express or implied, as to the accuracy, reliability, completeness, appropriateness, or sufficiency for any purpose of any information contained herein. Forstrong and its affiliates and related entities disclaim any and all liability relating to the information herein, including, without limitation, any express or implied representations or warranties for, statements contained in, and omissions from, the information. Forstrong and its affiliates and related entities are not liable for any errors or omissions in any information herein or for any loss or damage suffered, whether direct or consequential, resulting from the use of these materials.
The information contained in these materials is strictly for general illustrative, educational, or informational purposes, and is not intended to provide legal, investment, accounting, or tax advice, and should not be relied upon in that regard. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. These views are not and may not be relied upon as investment advice. Any opinion or assumption may contain elements of subjective judgment and are not intended to imply, nor should be interpreted as conveying, any form of guarantee or assurance by Forstrong of any future action or performance. Neither Forstrong nor any of its affiliates, businesses, or representatives make any representation or warranty, express or implied, as to the accuracy, reliability, completeness, appropriateness, or sufficiency for any purpose of any information contained herein. Forstrong and its affiliates and related entities disclaim any and all liability relating to the information herein, including, without limitation, any express or implied representations or warranties for, statements contained in, and omissions from, the information. Forstrong and its affiliates and related entities are not liable for any errors or omissions in any information herein or for any loss or damage suffered, whether direct or consequential, resulting from the use of these materials.
Any specific companies, issuers, funds, ETFs, or indices mentioned are for illustrative or educational purposes only and are not and shall not be deemed to be a recommendation to buy or sell any securities. Any companies, issuers, funds, or ETFs mentioned do not necessarily represent current or future holdings of any Forstrong funds or products. Any strategies discussed are strictly for illustrative and educational purposes and are not a recommendation, offer, or solicitation to buy or sell any securities or to adopt any investment strategy. There is no guarantee that any strategies discussed will be effective.
Commissions, fees, and expenses all may be associated with investments in Forstrong funds, ETFs, and/or other investment products. Please read a fund’s offering memorandum or ETF’s prospectus, as applicable, which contains detailed information, and speak to an advisor before investing. Funds and ETFs are not guaranteed, their values change frequently, and investors may experience a gain or loss. Past performance may not be repeated.
Certain statements in these materials may contain forward-looking statements or forward-looking information that are predictive in nature and may include words such as “expects”, “anticipates”, “intends”, “plans”, believes”, “estimates”, and similar forward-looking expressions or negative versions thereof. Such forward-looking statements are based on current expectations and projections about future general economic, political, and other relevant market factors, such as interest, and assuming no changes to applicable tax or other laws or regulations. Expectations and projections about future events are inherently subject to, among other things, risks and uncertainties, some of which may be unforeseeable and, accordingly, may prove to be incorrect at a future date. Forward-looking statements are not guarantees of future performance, and actual events could differ materially from those expressed or implied in any forward-looking statements. A number of important factors can contribute to these differences, including, but not limited to, general economic, political, and market factors in Canada and internationally, interest and foreign exchange rates, global equity and capital markets, business competition, and catastrophic events. You should avoid placing any undue reliance on forward-looking statements. Past performance is no indicator of future performance and the materials are not intended to forecast or predict future events. Forstrong disclaims any and all responsibility to update any forward-looking statements, whether as a result of new information, future events, or otherwise, except as specifically required by law.
The index returns are shown for illustrative or informational purposes only. Indexes are unmanaged, and index performance does not include the impact of fees, commissions, and transaction costs and expenses that would be payable by investors in investment products that seek to track an index. Such costs would lower performance. It is not possible to invest directly in an index. Past performance does not guarantee future results. Index performance does not represent actual fund performance.
The allocation information shown above is for general informational purposes only and is intended to provide only a summary overview of Forstrong’s historical allocation methodologies over the indicated periods shown above. The above information is not meant to illustrate specific allocations or exposures within any particular Forstrong fund or product, including Forstrong exchange-traded funds (ETFs). The above information is historical in nature only and is not indicative of future results or actions. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. Graphs and charts are used for illustrative purposes only. The information, analysis, and opinions expressed herein are for general information only and are not intended to provide specific advice or recommendations for any individual or entity.
Commissions, fees, and expenses all may be associated with investments in Forstrong funds, ETFs, and/or other investment products. Please read a fund’s offering memorandum or ETF’s prospectus, as applicable, which contains detailed information, and speak to an advisor before investing. The indicated rates of return are the historical annual compounded total returns including changes in unit value and reinvestment of all distributions and do not take into account sales, redemption, distribution or optional charges or income taxes payable by any securityholder that would have reduced returns. Funds and ETFs are not guaranteed, their values change frequently, and investors may experience a gain or loss. Past performance may not be repeated.
The information contained herein is presented solely for illustrative purposes and should not be construed as a forecast or projection. While some information used herein has been obtained from various published and unpublished third-party sources considered to be reliable, such information has not been independently verified by Forstrong (and Forstrong disclaims any obligation to verify) and Forstrong does not guarantee its accuracy or completeness and accepts no liability for any loss or damage suffered, whether direct or consequential, resulting from its use. It should be noted that data provided may be approximate numbers.
©2026 Forstrong Global Asset Management Inc. All rights reserved.
Forstrong Global® and the Forstrong Global® logo are trademarks or registered trademarks of Forstrong Global Asset Management Inc. in Canada.