
Strategy Dashboard
Buying Time
Q3 2026
US Treasury Secretary Scott Bessent has had a busy summer. In mid-August, the Treasury unexpectedly announced that it would at least double the size of its liquidity-support buybacks for 10-to-30-year bonds. The move came shortly after 30-year Treasury yields reached their highest level since 2007. Only weeks earlier, the US had joined Japan in a rare, coordinated intervention to support the yen. After decades of generally allowing financial markets to find their own equilibrium, is the Treasury becoming an increasingly active participant?
The bond buybacks warrant some important clarification. They are not quantitative easing. The Treasury will purchase and retire older, less-liquid securities, but this does not reduce the government’s overall borrowing requirements. Any cash used must ultimately be financed through revenues or additional debt issuance elsewhere. The amounts are also modest relative to the $32 trillion Treasury market. Still, signaling matters. Long-term yields fell sharply following the announcement, although much of the initial move was subsequently reversed.
The currency intervention may be related. On July 31st, the US Treasury sold euros from its Exchange Stabilization Fund and purchased yen alongside Japan’s Ministry of Finance. This marked the first coordinated effort to strengthen the Japanese currency since 1998. The yen’s decline had become increasingly disorderly, intensifying imported inflation and increasing pressure on the Bank of Japan to tighten monetary policy more aggressively.
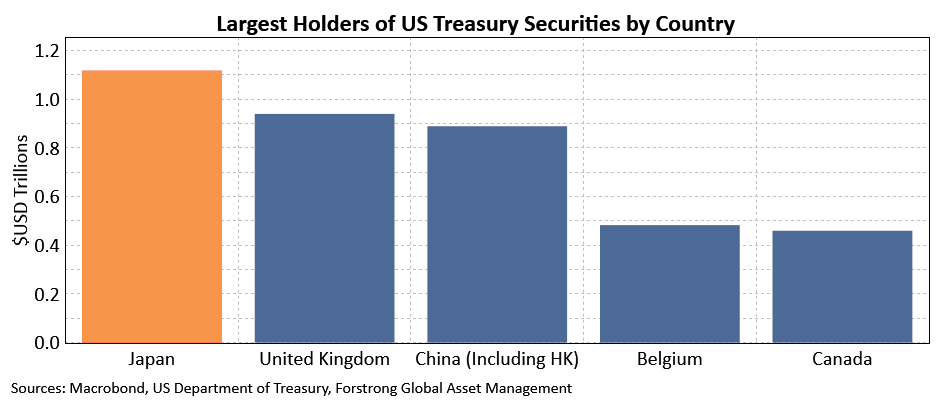
Per the chart below, Japan remains the largest foreign holder of US Treasury securities, with approximately $1.1 trillion. Japan typically finances yen purchases by drawing down its foreign currency reserves, potentially including Treasury holdings. Repeated interventions could therefore place additional upward pressure on US yields. Notably, Japan has indicated that it plans to access the Federal Reserve’s Foreign and International Monetary Authorities repo facility, allowing it to borrow dollars against its Treasuries rather than sell them outright. Viewed in this light, US participation may have been intended not only to support the yen, but also to prevent instability in one market from spilling into another.
These actions are understandable. Disorderly currency and bond market moves can quickly tighten financial conditions, raise borrowing costs and spill over into risk assets like equities. But there is a limit to what market intervention can accomplish. The US fiscal deficit is projected to remain near 6% of GDP this year, federal debt has surpassed $40 trillion and rising interest costs are consuming a growing share of federal expenditures. Buybacks can improve market liquidity, but they cannot resolve the underlying supply-demand imbalance.
There is also credibility risk. Treasury debt management has historically emphasized “regular and predictable” issuance. If investors begin to view buybacks as an attempt to manipulate yields rather than improve liquidity, they may demand a higher term premium to compensate for policy uncertainty. In that scenario, intervention could ultimately become self-defeating.
For investors, fiscal credibility, foreign demand and currency volatility are becoming increasingly important drivers of the Treasury market. Higher yields have restored income and portfolio-hedging potential, but elevated uncertainty argues for a cautious approach to duration and continued diversification across inflation-protected bonds, currencies and real assets. The Treasury may be buying bonds and yen, but what it is really trying to buy is time.
Cash & Currencies
We remain invested with a view of continuing resilient global growth, despite a challenging geopolitical environment and renewed inflationary pressure. However, downside risks are elevated, as higher interest rates impact consumers and businesses, while global central banks are forced to adjust monetary policy settings. We have increased cash and equivalents exposure this quarter.
Bonds
We continue to like local currency emerging markets (EM) sovereign bonds for their high yield, diversification benefits and strong underlying fundamentals. However, with an inflationary resurgence in developed and emerging markets alike, EM monetary policy tailwinds have receded; weakening the investment case at the margin. We have trimmed our exposure to local currency emerging markets sovereign bonds this quarter.
Equities
European equity earnings should remain well-supported by a nascent growth recovery across the continent. However, the energy price spike and a hawkish-leaning European Central Bank present near-term risks to the economic momentum. We have trimmed our exposure to European equities this quarter.
Opportunities
Indian stocks have seen an exodus of foreign investor capital of late and are susceptible to further disruption from AI in the near-term. Conversely, we viewed a recent pullback in copper mining equities as an opportunity to add to a position well-supported by durable global demand trends for the foreseeable future. We have liquidated our position in Indian equities in growth-oriented strategies and added to our exposure to copper mining equities in balanced and growth-oriented strategies this quarter.

Looking for perspective beyond the headlines?
The information contained in these materials is for general informational purposes only and is intended to provide only brief comments on broad market, industry or sector trends, or other general economic or market conditions. It is not intended to provide an overview of the terms applicable to any products or funds managed or sponsored by Forstrong Global Asset Management Inc. (“Forstrong”). Views expressed regarding a particular company, security, industry, investment, or market sector are the views only of that individual as of the time expressed and do not necessarily represent the views of Forstrong or any other person in the Forstrong organization. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. These views are not and may not be relied upon as investment advice and, because investment decisions for a Forstrong fund or product are based on numerous factors, are not and should not be relied upon as an indication of trading intent on behalf of any Forstrong fund or product. Any opinion or assumption may contain elements of subjective judgment and are not intended to imply, nor should be interpreted as conveying, any form of guarantee or assurance by Forstrong of any future action or performance. Neither Forstrong nor any of its affiliates, businesses, or representatives make any representation or warranty, express or implied, as to the accuracy, reliability, completeness, appropriateness, or sufficiency for any purpose of any information contained herein. Forstrong and its affiliates and related entities disclaim any and all liability relating to the information herein, including, without limitation, any express or implied representations or warranties for, statements contained in, and omissions from, the information. Forstrong and its affiliates and related entities are not liable for any errors or omissions in any information herein or for any loss or damage suffered, whether direct or consequential, resulting from the use of these materials.
The information contained in these materials is strictly for general illustrative, educational, or informational purposes, and is not intended to provide legal, investment, accounting, or tax advice, and should not be relied upon in that regard. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. These views are not and may not be relied upon as investment advice. Any opinion or assumption may contain elements of subjective judgment and are not intended to imply, nor should be interpreted as conveying, any form of guarantee or assurance by Forstrong of any future action or performance. Neither Forstrong nor any of its affiliates, businesses, or representatives make any representation or warranty, express or implied, as to the accuracy, reliability, completeness, appropriateness, or sufficiency for any purpose of any information contained herein. Forstrong and its affiliates and related entities disclaim any and all liability relating to the information herein, including, without limitation, any express or implied representations or warranties for, statements contained in, and omissions from, the information. Forstrong and its affiliates and related entities are not liable for any errors or omissions in any information herein or for any loss or damage suffered, whether direct or consequential, resulting from the use of these materials.
Any specific companies, issuers, funds, ETFs, or indices mentioned are for illustrative or educational purposes only and are not and shall not be deemed to be a recommendation to buy or sell any securities. Any companies, issuers, funds, or ETFs mentioned do not necessarily represent current or future holdings of any Forstrong funds or products. Any strategies discussed are strictly for illustrative and educational purposes and are not a recommendation, offer, or solicitation to buy or sell any securities or to adopt any investment strategy. There is no guarantee that any strategies discussed will be effective.
Commissions, fees, and expenses all may be associated with investments in Forstrong funds, ETFs, and/or other investment products. Please read a fund’s offering memorandum or ETF’s prospectus, as applicable, which contains detailed information, and speak to an advisor before investing. Funds and ETFs are not guaranteed, their values change frequently, and investors may experience a gain or loss. Past performance may not be repeated.
Certain statements in these materials may contain forward-looking statements or forward-looking information that are predictive in nature and may include words such as “expects”, “anticipates”, “intends”, “plans”, believes”, “estimates”, and similar forward-looking expressions or negative versions thereof. Such forward-looking statements are based on current expectations and projections about future general economic, political, and other relevant market factors, such as interest, and assuming no changes to applicable tax or other laws or regulations. Expectations and projections about future events are inherently subject to, among other things, risks and uncertainties, some of which may be unforeseeable and, accordingly, may prove to be incorrect at a future date. Forward-looking statements are not guarantees of future performance, and actual events could differ materially from those expressed or implied in any forward-looking statements. A number of important factors can contribute to these differences, including, but not limited to, general economic, political, and market factors in Canada and internationally, interest and foreign exchange rates, global equity and capital markets, business competition, and catastrophic events. You should avoid placing any undue reliance on forward-looking statements. Past performance is no indicator of future performance and the materials are not intended to forecast or predict future events. Forstrong disclaims any and all responsibility to update any forward-looking statements, whether as a result of new information, future events, or otherwise, except as specifically required by law.
The index returns are shown for illustrative or informational purposes only. Indexes are unmanaged, and index performance does not include the impact of fees, commissions, and transaction costs and expenses that would be payable by investors in investment products that seek to track an index. Such costs would lower performance. It is not possible to invest directly in an index. Past performance does not guarantee future results. Index performance does not represent actual fund performance.
The allocation information shown above is for general informational purposes only and is intended to provide only a summary overview of Forstrong’s historical allocation methodologies over the indicated periods shown above. The above information is not meant to illustrate specific allocations or exposures within any particular Forstrong fund or product, including Forstrong exchange-traded funds (ETFs). The above information is historical in nature only and is not indicative of future results or actions. These materials contain information and views as of the date indicated and such information and views are subject to change at any time without notice, based upon market and other conditions, and Forstrong disclaims any and all responsibility to update such information and views. Graphs and charts are used for illustrative purposes only. The information, analysis, and opinions expressed herein are for general information only and are not intended to provide specific advice or recommendations for any individual or entity.
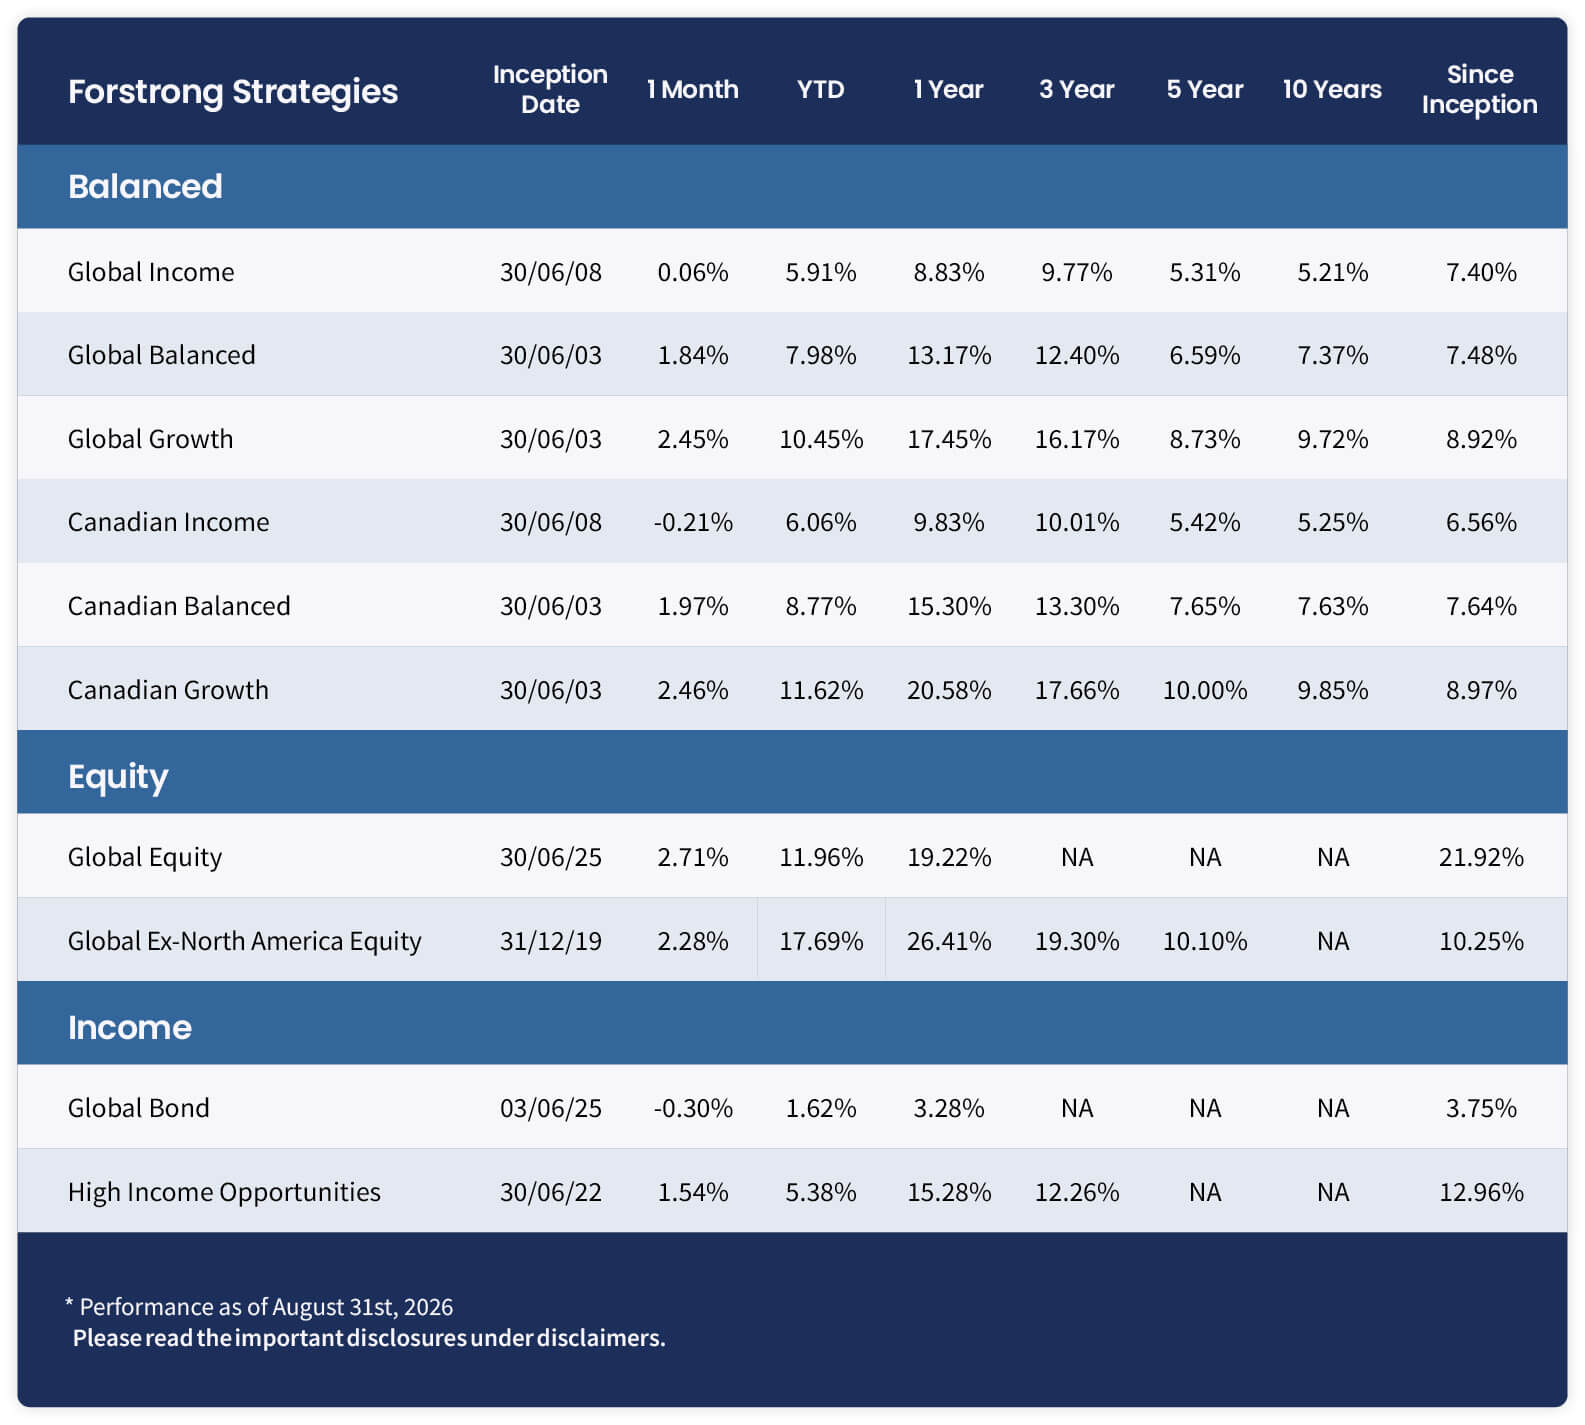
Commissions, fees, and expenses all may be associated with investments in Forstrong funds, ETFs, and/or other investment products. Please read a fund’s offering memorandum or ETF’s prospectus, as applicable, which contains detailed information, and speak to an advisor before investing. The indicated rates of return are the historical annual compounded total returns including changes in unit value and reinvestment of all distributions and do not take into account sales, redemption, distribution or optional charges or income taxes payable by any securityholder that would have reduced returns. Funds and ETFs are not guaranteed, their values change frequently, and investors may experience a gain or loss. Past performance may not be repeated.
The information contained herein is presented solely for illustrative purposes and should not be construed as a forecast or projection. While some information used herein has been obtained from various published and unpublished third-party sources considered to be reliable, such information has not been independently verified by Forstrong (and Forstrong disclaims any obligation to verify) and Forstrong does not guarantee its accuracy or completeness and accepts no liability for any loss or damage suffered, whether direct or consequential, resulting from its use. It should be noted that data provided may be approximate numbers.
©2026 Forstrong Global Asset Management Inc. All rights reserved.
Forstrong Global® and the Forstrong Global® logo are trademarks or registered trademarks of Forstrong Global Asset Management Inc. in Canada.